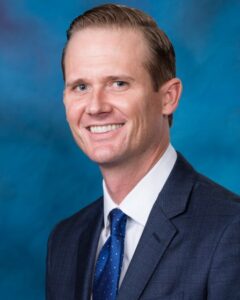
The Federal Reserve’s September rate increase raised fresh questions about how borrowers on floating-rate asset-based lending (ABL) facilities are managing liquidity, pricing and growth. To find out what is changing, and what is not, Rita E. Garwood, editor in chief of ABF Journal, spoke with Jon Biorkman, Head, U.S. Specialty Finance at BMO.
Biorkman discusses utilization trends, working capital management, acquisition financing, underwriting and what borrowers and lenders should watch heading into 2027. His central message: Rates matter, but they are only one part of a bigger picture.
Rita Garwood: The Fed raised rates in September. How are middle-market borrowers managing liquidity differently now that the increase is in effect, compared with the past few months?
Jon Biorkman: The September rate increase is certainly an important data point, but it has not materially changed the broader approach to liquidity management. Middle-market companies remain focused on balancing disciplined execution with long-term strategic objectives.
Management teams are carefully managing working capital while maintaining flexibility to respond to changing market conditions and invest in growth opportunities.
Ultimately, the focus is on preserving financial resilience while positioning the business to capitalize on opportunities as they emerge.
Garwood: ABL is typically priced off a floating rate. How are borrowers responding to higher borrowing costs, and are you seeing them draw on their lines less, renegotiate pricing or hedge?
Biorkman: Interest-rate management remains an ongoing discussion between borrowers and lenders, making the recent rate move part of a broader conversation rather than a significant shift.
How a company responds often depends on factors beyond the stated interest rate, including its cash conversion cycle, seasonality, operating performance and overall capital structure.
Some clients have implemented hedging strategies, while others have focused on improving working capital efficiency or optimizing their capital structure. In our experience, most companies are taking a holistic view of liquidity and cost of capital, with the discussion centered on maintaining financial flexibility while supporting the needs of the business.
Garwood: Which industries or borrower profiles are still drawing heavily on their asset-based lines, and which are pulling back? What is driving the difference?
Biorkman: We are not seeing a broad pullback in ABL utilization tied to higher rates alone. Utilization is generally strongest among borrowers experiencing growth, working capital expansion or cyclical recovery. For example, portions of the transportation sector are emerging from a prolonged downturn and using ABL facilities to support increased activity and associated working capital needs.
Conversely, utilization may be lower among borrowers with stronger cash generation, reduced working capital requirements or access to alternative sources of capital. In those situations, ABL often serves more as a liquidity backstop than a primary funding source.
Ultimately, utilization is driven by three factors: growth, working capital needs and the role the ABL facility plays within the broader capital structure.
Garwood: How are borrowers managing working capital, particularly inventory and receivables, with financing more expensive? Can you share an example, without naming the client, of a strategy that’s working?
Biorkman: In a higher-cost financing environment, effective working capital management is more important than ever. Successful companies are taking a disciplined approach to the cash conversion cycle, managing inventory more closely, accelerating collections where possible and working collaboratively with suppliers and customers to optimize cash flow. The most effective strategies result from alignment across procurement, operations and sales to improve overall cash efficiency.
Garwood: Are higher rates changing what borrowers want from a facility, such as size, availability, or structure, compared with earlier this year?
Biorkman: Flexibility remains the primary consideration. Even when utilization levels are modest, borrowers continue to value access to liquidity, particularly in an uncertain economic environment.
We are also seeing increased focus on structure. Borrowers are evaluating the right mix of revolving and term debt, the overall cost of capital and the flexibility needed to support growth, acquisitions and working capital requirements.
While higher rates have increased scrutiny around capital allocation and investment decisions, they have not diminished the importance of liquidity. If anything, borrowers are placing a greater premium on financing structures that provide both certainty and flexibility.
Garwood: How is M&A activity among middle-market companies holding up after the increase, and what role is ABL playing in acquisition financing?
Biorkman: M&A remains an important growth strategy for many middle-market companies. While higher rates may influence valuations, we continue to see both strategic buyers and private equity sponsors pursue acquisitions that align with their long-term objectives.
ABL plays an important role in acquisition financing because it allows borrowers to maximize the value of their working-capital assets and can provide a cost-effective source of capital. In many transactions, ABL is paired with term debt to create a capital structure that balances liquidity, flexibility and financing costs.
Garwood: BMO is expected to roughly double new ABL client originations in 2026 vs. 2025. What is behind that growth, and how do higher rates factor in, if at all?
Biorkman: Our growth is being driven by a deliberate investment in the client experience. This year, we aligned our organizational structure around dedicated origination, underwriting and portfolio-management teams, allowing us to deliver greater speed, responsiveness and certainty of execution.
At the same time, we believe BMO’s differentiation is rooted in local relationship delivery, deep industry expertise, advisory solutions and our ability to bring the full bank to clients as one team. Companies are increasingly looking for banking partners that can provide strategic insights and a broad range of capabilities as their needs evolve.
While interest rates play a role in financing decisions, we believe our growth reflects the investments we’ve made in our people and platform, while always keeping the client first.
Garwood: Flexibility is becoming a bigger factor in financing decisions. What does that mean in practice, and which terms are borrowers prioritizing now that rates are higher?
Biorkman: In practice, flexibility means ensuring a company has access to liquidity when conditions change. Borrowers want financing solutions that can support growth, acquisitions, seasonal needs and unexpected market shifts without requiring frequent restructuring.
As a result, they’re increasingly focused on borrowing availability, incremental liquidity capacity, covenant flexibility and the ability to scale their facilities alongside the business. In today’s environment, flexibility can be just as important as pricing.
Garwood: Some borrowers have considered moving from cash-flow lending to ABL. Does the rate environment make that case stronger or weaker, and what should a company weigh before deciding?
Biorkman: A higher-rate environment tends to encourage companies to reassess all available financing alternatives, including whether an asset-based structure may better align with their needs.
That said, the decision shouldn’t be based solely on pricing. Companies should evaluate their asset base, borrowing needs, operational requirements, reporting capabilities and long-term strategic objectives. Many ABL facilities also offer greater flexibility through borrowing-base driven structures and, in some cases, a lighter covenant package than traditional cash-flow facilities. For the right company, ABL can provide both increased liquidity and greater financial flexibility.
Garwood: Have higher rates changed how ABL lenders like BMO approach underwriting or collateral monitoring?
Biorkman: Interest rates are certainly an important consideration when evaluating a borrower’s financial profile, particularly when assessing fixed-charge coverage and overall debt capacity. However, rates are only one component of a broader underwriting framework.
We continue to focus on core fundamentals, including collateral quality, cash-flow generation, management execution, industry trends and broader macroeconomic conditions. Effective ABL underwriting has always required a comprehensive view of risk, and that remains true regardless of where rates are moving.
Garwood: Looking ahead to 2027, what is the biggest risk or opportunity for middle-market borrowers and ABL lenders, and how should each prepare?
Biorkman: One area that both borrowers and lenders should continue to monitor is asset valuation. Certain industries have benefited from elevated inventory values and strong demand dynamics over the past several years. If market conditions, trade flows or commodity prices shift, those values could normalize.
For borrowers, preparation means maintaining discipline around inventory management, liquidity planning and operational flexibility. For lenders, it means closely monitoring collateral trends and ensuring capital structures remain appropriate under a variety of economic scenarios.
The biggest opportunity is that periods of change often create opportunities for well-prepared companies. Organizations that maintain strong liquidity, adapt quickly and make disciplined capital-allocation decisions are often the ones best positioned to grow through market transitions.
Conclusion
Biorkman’s answers return to a common thread: Rates are one input, not the whole story. For borrowers and lenders alike, the priorities he describes remain liquidity, flexibility and discipline.